HELOC vs cash-out refinance, which is better?
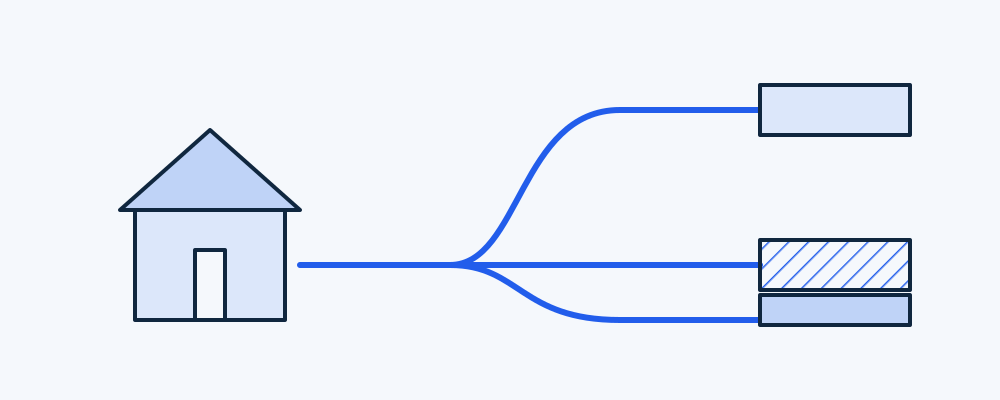
Both let you tap home equity. The right tool depends on what you need the money for, how long you need it, and what your current first mortgage looks like.

Compare three loan structures, calculate potential access, stress-test variable rates and use a fillable comparison worksheet.
Free fillable PDF. No email or signup required. Educational information, not a loan offer or personalized advice.
Every product, use case, and comparison in one place.
A home equity line of credit (HELOC) sits behind your existing first mortgage. You keep your first loan untouched and open a separate line of credit against your equity. You can draw from it like a credit card during the draw period, and you usually pay variable interest on what you use.
A cash-out refinance replaces your existing first mortgage with a new, larger loan. You take the difference in cash. The new loan has its own rate, term, and payment.
A HELOC usually wins when your current first mortgage has very favorable terms you do not want to touch, when you need access to funds over time rather than all at once, or when you want flexibility to borrow, repay, and borrow again.
A cash-out refinance usually wins when you want one new fixed payment, when you are consolidating higher-interest debt and want predictability, or when your current first mortgage no longer fits your situation.
Run the comparison with real numbers before you commit. The HELOC vs cash-out comparison calculator models both side by side over a timeframe you choose. Pair that with the deeper article on this exact decision to see how the trade-offs play out in practice.
The most common mistake I see is treating equity as free money. It is not. It is a tool with a cost. Build the plan first, then pick the tool.
Equity is one of the most useful financial tools most homeowners have. It is also one of the easiest to misuse. The right product depends on what the money is for, how long you need it, and what your current first mortgage looks like.
Related glossary terms

Compare three loan structures, calculate potential access, stress-test variable rates and use a fillable comparison worksheet.
Free fillable PDF. No email or signup required. Educational information, not a loan offer or personalized advice.
Both let you tap home equity. The right tool depends on what you need the money for, how long you need it, and what your current first mortgage looks like.
Optional and free mortgage education by email for buyers and homeowners. No account required. Unsubscribe anytime.